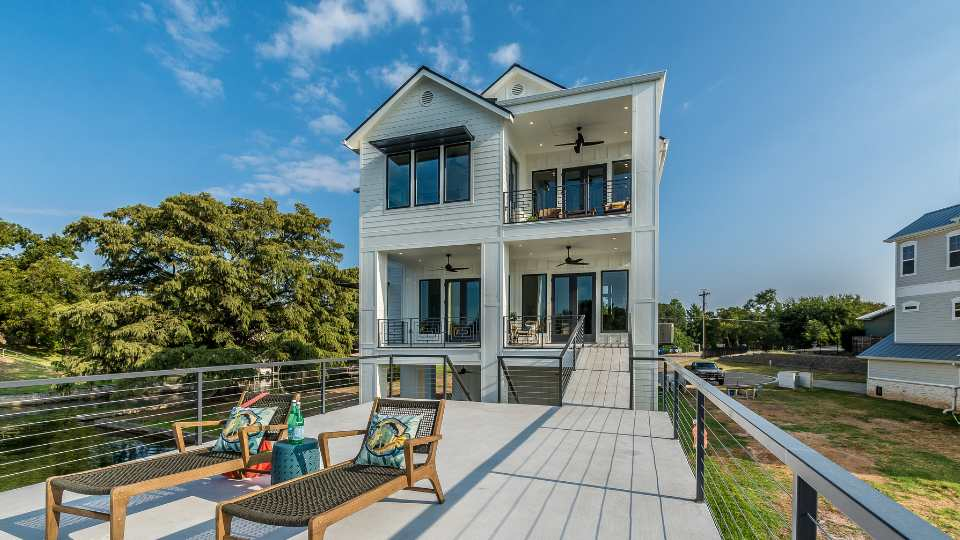
Buy a Florida Vacation Home for Tax Savings: Essential Guide

Buying a vacation home in Florida can do more than offer a place to unwind—it can also create meaningful tax advantages. Owning a Florida vacation property can lower annual tax costs through relatively low property tax rates, potential mortgage interest deductions, and possible rental income offsets. For those who plan carefully, these benefits can make a second home in the Sunshine State a strategic financial move.
Florida’s tax environment stands out for its lack of state income tax and homeowner-friendly policies. Property tax assessments tend to be moderate, and programs like the Homestead Exemption can significantly reduce taxable value for qualifying primary residences. These factors make Florida appealing not just for its beaches and weather, but for its long-term financial potential.
A closer look at how property taxes, mortgage deductions, and rental income rules apply to vacation homes reveals opportunities to save while staying compliant. Understanding these details helps buyers make informed decisions and maximize the financial value of their investment.
The information provided in this website was derived from sources deemed to be reliable to is not guaranteed or warranted. All information, content, and materials available on this site are for general informational purposes only and are not intended to be legal, financial or tax advice.
The information contained herein is not a substitute for professional legal, financial or tax consultation and should not be relied upon for any legal, financial, or tax matters. If you require legal, financial or tax assistance, please consult with a qualified attorney, financial or tax professional who can provide guidance tailored to your specific situation.
Understanding Tax Benefits of Buying a Florida Vacation Home
Florida homeowners often gain financial advantages through state and federal tax provisions tied to second homes. The absence of a state income tax, potential deductions for mortgage interest and property taxes, and opportunities for rental income deductions can make a vacation home more cost-efficient over time.
Overview of Tax Benefits
Florida’s no state income tax policy immediately benefits residents and nonresidents who own property in the state. Owners don’t pay income tax on rental profits earned from their vacation homes.
Federal tax rules may allow deductions for mortgage interest and property taxes on a second home, though these depend on how the property is used. If rented, owners can also deduct related expenses such as maintenance, insurance, and management fees.
| Common Deductible Expenses | Example Items |
|---|---|
| Mortgage Interest | Interest paid on qualified home loans |
| Property Taxes | Annual local property tax payments |
| Rental Expenses | Repairs, advertising, and cleaning costs |
Florida’s property tax rates are often lower than in many other states, and local exemptions—such as the Homestead Exemption for primary residences—can provide additional relief if the home later becomes a primary dwelling.
Key Differences Between Primary and Vacation Homes
A primary residence qualifies for the Homestead Exemption, which can reduce the taxable value of the property and cap annual assessment increases. A vacation home, however, doesn’t qualify unless it becomes the owner’s permanent residence.
This distinction affects both property tax liability and eligibility for capital gains exclusions. When selling a primary home, owners may exclude a portion of gains from federal taxes, but that exclusion generally doesn’t apply to a second home.
Florida homeowners who rent out their vacation property must also report rental income. If the property is rented fewer than 15 days per year, that income is usually tax-free, but expenses can’t be deducted. Once rented more frequently, the IRS treats it as a mixed-use property with specific reporting rules.
How Second Home Status Affects Tax Savings
The IRS defines a second home as a property used personally for more than 14 days per year or more than 10% of the days it’s rented. Meeting this threshold allows owners to claim mortgage interest and property tax deductions similar to a primary residence.
If the home is primarily an investment property, owners may use a 1031 exchange to defer capital gains taxes when selling and reinvesting in another property. This can preserve equity and support long-term real estate growth.
Maintaining accurate records of usage days, rental periods, and expenses is essential. These details determine whether the home qualifies for personal-use deductions or rental-related write-offs, directly influencing the overall tax savings available to Florida vacation homeowners.
Property Taxes and Assessment for Florida Vacation Homes
Florida homeowners who purchase vacation properties face unique tax considerations. Property taxes depend on assessed value, classification, and local millage rates, while non-homestead rules and recent legislative updates influence annual increases and potential savings.
How Property Taxes Are Calculated
Florida uses a millage rate system to determine property taxes. One mill equals $1 per $1,000 of assessed property value. For example, a vacation home assessed at $400,000 with a 20-mill rate would owe $8,000 in annual property taxes.
Vacation homes are classified as non-homestead properties, meaning they are not eligible for the homestead exemption that protects primary residences. Without this exemption, owners pay taxes on the full assessed value.
Local governments set millage rates annually based on budget needs. Counties with higher service demands, such as coastal or tourist-heavy areas, often impose higher rates. Florida homeowners who rent their vacation properties must also account for potential local business taxes or tourist development taxes that apply to short-term rentals.
Assessment Processes and Local Variations
County property appraisers determine the assessed value of each vacation home. Assessments generally reflect market value as of January 1 each year. Appraisers consider factors such as property condition, improvements, location, and comparable sales.
Local variation plays a major role. A home near a beach or entertainment district may be assessed higher than one inland. Some counties adjust values more aggressively in response to rising real estate markets.
Florida’s non-homestead assessment limitation restricts annual increases in assessed value to 10% per year, helping stabilize tax bills even when market prices surge. However, this cap does not apply in the first year of ownership, so new buyers often experience a sharp jump in property taxes after purchase.
| Factor | Impact on Assessment |
|---|---|
| Location | Higher near coastal or tourist areas |
| Property Condition | Renovations increase value |
| Market Trends | Rising prices lead to higher assessments |
Recent Changes in Property Tax Laws
Recent updates to Florida property tax laws have refined how assessments and exemptions apply to non-homestead properties. The 10% assessment cap remains in effect, but counties continue to adjust how they interpret “market value” during reassessments.
Legislation has also clarified short-term rental classifications. Properties rented for extended periods may qualify for certain deductions, while frequent short-term rentals are treated as income-generating assets subject to additional taxes.
Several counties have improved transparency by offering online assessment tools and appeal portals, allowing homeowners to review and dispute valuations more easily. These updates aim to balance local revenue needs with fair taxation for Florida vacation homeowners.
Homestead Exemption: Eligibility and Impact
Florida’s homestead exemption offers significant property tax relief to residents who make their home their permanent residence. It lowers the taxable value of a property, provides legal protections, and allows homeowners to transfer part of their tax savings when moving within the state.
Requirements for Homestead Exemption
To qualify, the homeowner must own and occupy the property as a permanent residence as of January 1 of the tax year. The property must serve as the owner’s primary domicile, not a secondary or vacation home.
Applicants typically need to provide:
- Proof of ownership (deed or property record)
- Florida driver’s license or ID showing the property address
- Voter registration or vehicle registration in Florida
The exemption applies only to individuals who are Florida residents. Nonresidents or those claiming residency in another state do not qualify. Homeowners must file an initial application with the county property appraiser’s office, usually by March 1.
Once approved, the exemption automatically renews each year, as long as the property remains the owner’s permanent residence. Any change in ownership or use requires notification to the property appraiser to avoid penalties or fines.
Benefits of the Homestead Exemption
The exemption reduces the assessed value of a primary residence by up to $50,000 for property tax purposes. The first $25,000 applies to all property taxes, while the second $25,000 applies only to non-school taxes.
This reduction can lower annual property taxes by several hundred dollars, depending on the local tax rate. In addition, Florida’s Save Our Homes cap limits increases in assessed value to 3% per year or the rate of inflation, whichever is lower.
Beyond tax savings, the homestead exemption provides legal protection from certain creditors, shielding the primary residence from forced sale under most circumstances. This combination of financial and legal benefits makes the exemption one of the most valuable tools for Florida homeowners seeking long-term stability.
Portability and Transferring Tax Savings
Florida allows homeowners to transfer part of their Save Our Homes benefit when moving to a new primary residence within the state. This feature, called portability, helps maintain lower property taxes even after purchasing a new home.
Homeowners can transfer up to $500,000 of their accumulated assessment difference to the new property. To qualify, they must establish the new home as their permanent residence within two years of leaving the previous one.
The process requires filing a Portability Application (Form DR-501T) with the property appraiser. This rule encourages mobility within Florida while preserving tax advantages, making it an important consideration for those upgrading or downsizing their homes.
Maximizing Mortgage Interest Deduction
Florida homeowners and investors can reduce taxable income by properly applying mortgage interest deduction rules. Understanding how federal limits, second home eligibility, and home equity loan conditions interact helps ensure compliance while maximizing potential savings.
Mortgage Interest Deduction Rules
The mortgage interest deduction allows taxpayers to deduct interest paid on loans used to buy, build, or improve a qualified residence. In 2025, the deduction applies to mortgage debt up to $750,000 for loans originated after December 15, 2017, or $1 million for older loans.
To claim the deduction, taxpayers must itemize on Schedule A of their federal return. Standard deduction thresholds—$14,600 for single filers and $29,200 for married couples—mean itemizing only makes sense when combined deductions exceed these amounts.
Interest is deductible only for mortgages secured by a primary or secondary residence. Lenders issue Form 1098 each January reporting total interest paid. Taxpayers use this form to calculate eligible deductions.
| Rule | 2025 Requirement |
|---|---|
| Loan limit | $750,000 post-2017 / $1M pre-2017 |
| Property type | Primary and one second home |
| Deduction method | Itemized on Schedule A |
Deducting Interest on Second Homes
A second home or vacation home can qualify for the same mortgage interest deduction as a primary residence if it meets IRS requirements. The property must have sleeping, cooking, and bathroom facilities, and the loan must be secured by the property itself.
Owners can use the home personally or rent it part-time. However, if the property is rented for more than 14 days per year and personal use is limited, the deduction may shift to rental property rules under passive activity regulations.
Only two residences can qualify each year—a primary and one secondary. If multiple vacation homes exist, only one may be designated for the deduction. Interest on additional properties is not deductible unless treated as investment property with separate reporting.
Home Equity Loan Interest Considerations
Interest on home equity loans or HELOCs remains deductible only when the borrowed funds are used to buy, build, or substantially improve the property securing the loan. Using proceeds for personal expenses, such as debt consolidation or travel, eliminates deductibility.
The combined total of first mortgage and home equity debt must stay wit